
Schedule a Meeting With Thad Wellshear or Call 785-213-0740
“Third-Party Posts”
The following link/content may include information and statistical data obtained from and/or prepared by thirdparty sources that TGW Wealth Management, deems reliable but in no way does TGW Wealth Management guarantee its accuracy or completeness. TGW Wealth Management had no involvement in the creation of the content and did not make any revisions to such content. All such third-party information and statistical data contained herein is subject to change without notice and may not reflect the view or opinions of TGW Wealth Management. Nothing herein constitutes investment, legal or tax advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of TGW Wealth Management, execution of required documentation, and receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results.

Retirement in 2026: 7 Smart Moves to Turn Savings Into a Paycheck (and Sleep Better Doing It)
Retirement planning in 2026 isn’t just about “saving more.” It’s about building a reliable income plan, keeping taxes predictable, and making sure your money is positioned to handle inflation, market swings, and healthcare costs—all while staying aligned with your...

2026 Retirement Planning Goals: A Simple Roadmap to Start the Year Right
Kick off 2026 with clear retirement planning goals. Learn the 6 most important steps to protect your income, reduce taxes, and stay on track. 2026 Retirement Planning Goals: A Simple Roadmap to Start the Year Right A new year is the perfect time to reset...

Why Annuities Can Be a Great Fit Heading Into 2026
As we move into 2026, many investors are asking the same question: How do I protect what I’ve built—without giving up the ability to grow? That’s exactly where annuities can play a meaningful role. Annuities aren’t for everyone, and they’re not “one-size-fits-all,”...

Heading into 2026: A Smart Retirement Checkup (Without the Overwhelm)
As we turn the page into 2026, it’s the perfect time to run a simple “retirement checkup.” Not a stressful deep dive. Just a clear look at a few areas that tend to make the biggest difference—because small adjustments now can help protect your lifestyle later. Whether...
Fixed Indexed Annuities in 2026: A Smarter Way to Balance Growth and Protection in Your Retirement Portfolio
As we move into 2026, many retirees and pre-retirees are asking the same question: “How do I keep my retirement plan growing without exposing everything to the next market swing?” After several years of elevated volatility and changing interest-rate conditions, more...
Retirement Planning in 2026: Why Annuities Deserve a Serious Look
Retirement planning in 2026 looks different than it did even a few years ago. Many retirees and pre-retirees are facing a familiar challenge in a new way: they want growth, but they also want stability. They want income they can count on, but they don’t want to feel...
Safe Money Options Heading Into 2026
A Financial Advisor’s Guide to Protecting What You’ve Worked So Hard to Build When markets are choppy and headlines are loud, many people start asking the same question: “Where can I put my money so it feels safer, but still has a chance to grow?” As we move into...
Retirement Income Planning Going Into 2026: Turning Your Savings Into a Lifetime Paycheck
For most people, retirement isn’t about a specific age or account balance—it’s about confidence.Confidence that the bills will be paid, that you can handle surprises, and that you won’t run out of money before you run out of life. As we approach 2026, retirement...
Estate Planning & You: Getting Ready for 2026 (Without Freaking Out)
state planning sounds like something for billionaires in marble mansions… not for regular people with a mortgage, a 401(k), a dog, and a favorite taco spot. But here’s the truth:If you love someone or own something, you need some kind of estate plan. As we head toward...
By Andy Ives, CFP®, AIF® IRA Analyst It’s a new year, and the slate is wiped clean. Here we go again! While we are only one week into 2026, there are some important IRA and work plan transactions to be aware of: First RMDs. For anyone turning age 73 in 2026, this year...
Coming Soon: The Thrift Savings Plan Will Start Offering In-Plan Roth Conversions
By Ian Berger, JD IRA Analyst Since 2010, participants in certain private sector 401(k) plans have been able to boost their Roth retirement savings by doing an “in-plan Roth conversion” of non-Roth plan funds to a Roth account within the same plan. This plan feature...
Weekly Market Commentary
US markets ended the New Year holiday-shortened week with losses. Mega-cap Technology issues sold off on low volume, as did Financial and Consumer Discretionary sectors. That said, the S&P 500 posted its third straight year of double-digit gains as investors...
Weekly Market Commentary
The Christmas-shortened week produced gains across all major US indices, with the S&P 500 and Dow Jones hitting record highs. Mega-cap Tech assumed its leadership role with the semiconductor sector having relative strength. Nvidia announced a $20 billion deal...
Weekly Market Commentary
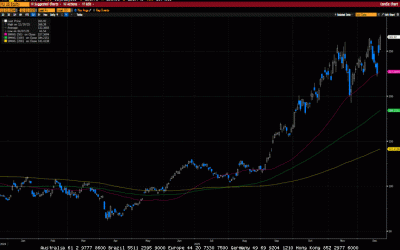
US markets finished the week mixed, with a late-week rally in technology mitigating early-week losses. Micron Technology’s third-quarter results were excellent and helped propel technology stocks after the announcement. Western Digital, Seagate, and Sandisk, other...
Weekly Market Commentary
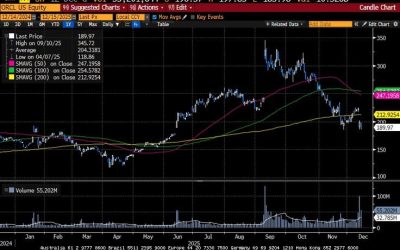
The Federal Reserve, as expected, cut its monetary policy rate by twenty-five basis points to 3.50%-3.75% and tempered expectations for further cuts in 2026. The decision was not unanimous, as a divided Fed considered elevated inflation against a weakening labor...
Weekly Market Commentary
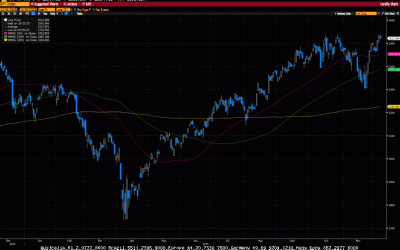
Apprehensive investors pushed markets higher this week, with the small-cap Russell 2000 hitting a new all-time high, while the S&P 500 closed just 50 points below its October all-time high. Economic data, some of which is quite dated, offered a mixed picture of...
Weekly Market Commentary
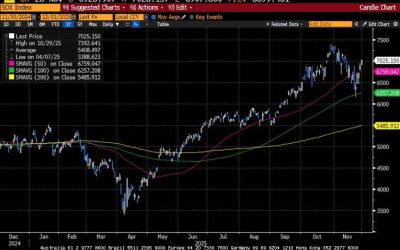
The holiday-shortened week saw global financial markets trade higher. Increased optimism for a December rate cut, along with some constructive news on the AI front, catalyzed buying across risk assets. Several Fed officials indicated they were inclined to support a...
Weekly Market Commentary
Financial markets continued to decline as investors sold AI-related stocks amid valuation concerns, while rotating into more defensive sectors such as healthcare and consumer staples. A stellar third-quarter earnings report from NVidia prompted investors to step in...

Ed Slott’s Elite IRA Advisor Group (Ed Slott Group) is a membership organization owned by Ed Slott and Company, LLC. Logos and/or trademarks are property of their respective owners and no endorsement of (TGW Wealth Management) is stated or implied. Ed Slott Group and Ed Slott and Company, LLC are not affiliated with TGW Wealth Management.
For the detailed requirements of Ed Slott’s Elite IRA Advisor Group, please visit: https://www.irahelp.com/
530A Trump Accounts: The Compounding Mathematical Facts
By Andy Ives, CFP®, AIF® IRA Analyst These days, anything with a hint of politics can be divisive. Trump accounts are no different. Public comments about this new savings vehicle are clearly rooted in the political divide that permeates our country. We are all sick up...
Not Child’s Play: How the “Kiddie Tax” Works
By Ian Berger, JD IRA Analyst With contributions to Trump accounts having gone live on July 4, 2026, there has been lots of discussion recently about the “kiddie tax.” That’s because, once a child reaches January 1 of the year they turn age 18, they will be able to...
Does the Five-Year Holding Period Pertain to Me?: Today’s Slott Report Mailbag
By Ian Berger, JD IRA Analyst QUESTION: My wife (Keiko) currently does not take a required minimum distribution (RMD) on her retirement account because the plan allows this while she is still working. Here are our questions: If she retires this December (2026), would...
What You Need to Know About the Still-Working Exception
By Sarah Brenner, JD Director of Retirement Education Tax rules require most retirement account owners who are subject to required minimum distributions (RMDs) to begin withdrawals at age 73. However, there is an exception to this rule for certain individuals who...
QCD Code Y: Optional Again in 2026
By Andy Ives, CFP®, AIF® IRA Analyst During our recent Ed Slott and Company’s Instant IRA Success workshop in Brooklyn, NY, we were presenting information about qualified charitable distributions (QCDs) when an audible groan emanated from the crowd. Over the...
Can You Recharacterize a Roth Conversion to Avoid IRMAA?: Today’s Slott Report Mailbag Thursday, July 16, 2026
By Sarah Brenner, JD Director of Retirement Education Question: Hello, I’m married, filing jointly, and I have been converting my traditional IRA to Roth this year. If I convert too much and trigger higher Income-Related Monthly Adjustment Amount (IRMAA) charges, can...
How Plan Loans Work
By Ian Berger, JD IRA Analyst The June 15, 2026 Slott Report outlined the barriers preventing 401(k) and other plan participants from accessing their plan funds while working. The June 24, 2026 article discussed in-plan withdrawals as one way around those barriers....
The Ghost-Life Rule Explained
By Sarah Brenner, JD Director of Retirement Education The SECURE Act of 2019 changed many rules for inherited IRAs. However, it left intact the rules for non-living (non-person) beneficiaries, such as an estate. For these non-designated beneficiaries (NDBs), the same...
The Pro-Rata Rule and the Still-Working Exception: Today’s Slott Report Mailbag
By Andy Ives, CFP®, AIF® IRA Analyst QUESTION: I just wanted to verify that a 403(b) plan is not subject to the pro-rata rule when doing a Roth IRA conversion. Can you please let me know if this is correct? Thanks! Lynn ANSWER: Lynn, You are correct. When doing a Roth...
The following link/content may include information and statistical data obtained from and/or prepared by thirdparty sources that TGW Wealth Management, deems reliable but in no way does TGW Wealth Management guarantee its accuracy or completeness. TGW Wealth Management had no involvement in the creation of the content and did not make any revisions to such content. All such third-party information and statistical data contained herein is subject to change without notice and may not reflect the view or opinions of TGW Wealth Management. Nothing herein constitutes investment, legal or tax advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of TGW Wealth Management, execution of required documentation, and receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results.
Medicare in 2026: What’s New, What’s Changing, and What Your Clients Should Do Now
2026 is shaping up to be one of the most “noticeably different” Medicare years in a while—not because the rules are unrecognizable, but because the cost and prescription-drug pieces are moving in ways that many beneficiaries will actually feel in their monthly budget....
read more
Medicare in 2026: What to Know, What to Review, and What to Do Next
If you’re on Medicare (or turning 65 soon), 2026 is a great year to get organized. Medicare isn’t “one-and-done.” Plans, costs, provider networks, and prescription coverage can change from year to year — and even small changes can affect your monthly budget and your...
read more
Medicare Advantage Heading Into 2026: What You Need to Know Before You Enroll
If you’re approaching 65, already on Medicare, or helping a loved one evaluate coverage, you’ve probably noticed something: Medicare Advantage plans are everywhere. And there’s a reason for that. More than half of all people on Medicare now choose a Medicare Advantage...
read more
Medicare Supplement Plans (Medigap) for 2025–2026
What to Know About Filling the Gaps in Original Medicare If you’re approaching Medicare or already enrolled, you’ve probably noticed something surprising:Original Medicare (Parts A & B) doesn’t cover everything. That’s where Medicare Supplement Insurance (also...
read more
Medicare Supplement Plans in 2026: What’s Changing, What’s Not, and What It Means for You
If you’re on Medicare — or getting close — you’ve probably heard people talk about “Medicare Supplement” or “Medigap” plans. You’ve also probably heard…👉 “Plan letters”👉 “Original Medicare only covers 80%”👉 “Rates keep going up every year.” It’s a lot. So let’s walk...
read more
Working Past 65? The New Rules of Medicare for Today’s “Unretired” Americans
If you’re turning 65, there’s a good chance you’re not retiring the way your parents did. Many of today’s 60-somethings are still working, consulting, starting businesses, helping with grandkids, or caring for aging parents. Life doesn’t magically slow down at 65—and...
read more

Your Annual Medicare Checklist: What to Review Before You Change Plans
Choosing or changing your Medicare coverage isn’t something to rush. Each year, your health needs, prescriptions, and budget can shift—and plans change too. Use this simple checklist so you can feel confident in your decision. 1) Confirm your doctors and hospitals are...
read more

7 Costly Medicare Mistakes (and How to Avoid Them)
1) Waiting too long to enroll If you miss your Initial Enrollment Period (the 7-month window around your 65th birthday) and don’t have qualifying employer coverage, you may face lifelong Part B and Part D penalties.Fix: Mark your IEP dates, or talk with an advisor 2–3...
read more

“Snowbird Medicare: A Two-State Plan That Actually Works”
Snowbird Medicare: A Two-State Plan That Actually Works If you split the year between two homes, you already know about duplicate utility bills and the art of packing one jacket that somehow works in two climates. But there’s one thing snowbirds often overlook: how to...
read more
Medicare in 2026: What’s New, What’s Changing, and What Your Clients Should Do Now
2026 is shaping up to be one of the most “noticeably different” Medicare years in a while—not because the rules are unrecognizable, but because the cost and prescription-drug pieces are moving in ways that many beneficiaries will actually feel in their monthly budget....
Medicare in 2026: What to Know, What to Review, and What to Do Next
If you’re on Medicare (or turning 65 soon), 2026 is a great year to get organized. Medicare isn’t “one-and-done.” Plans, costs, provider networks, and prescription coverage can change from year to year — and even small changes can affect your monthly budget and your...
Medicare Advantage Heading Into 2026: What You Need to Know Before You Enroll
If you’re approaching 65, already on Medicare, or helping a loved one evaluate coverage, you’ve probably noticed something: Medicare Advantage plans are everywhere. And there’s a reason for that. More than half of all people on Medicare now choose a Medicare Advantage...
Medicare Supplement Plans (Medigap) for 2025–2026
What to Know About Filling the Gaps in Original Medicare If you’re approaching Medicare or already enrolled, you’ve probably noticed something surprising:Original Medicare (Parts A & B) doesn’t cover everything. That’s where Medicare Supplement Insurance (also...
Medicare Supplement Plans in 2026: What’s Changing, What’s Not, and What It Means for You
If you’re on Medicare — or getting close — you’ve probably heard people talk about “Medicare Supplement” or “Medigap” plans. You’ve also probably heard…👉 “Plan letters”👉 “Original Medicare only covers 80%”👉 “Rates keep going up every year.” It’s a lot. So let’s walk...
Working Past 65? The New Rules of Medicare for Today’s “Unretired” Americans
If you’re turning 65, there’s a good chance you’re not retiring the way your parents did. Many of today’s 60-somethings are still working, consulting, starting businesses, helping with grandkids, or caring for aging parents. Life doesn’t magically slow down at 65—and...
Your Annual Medicare Checklist: What to Review Before You Change Plans
Choosing or changing your Medicare coverage isn’t something to rush. Each year, your health needs, prescriptions, and budget can shift—and plans change too. Use this simple checklist so you can feel confident in your decision. 1) Confirm your doctors and hospitals are...
7 Costly Medicare Mistakes (and How to Avoid Them)
1) Waiting too long to enroll If you miss your Initial Enrollment Period (the 7-month window around your 65th birthday) and don’t have qualifying employer coverage, you may face lifelong Part B and Part D penalties.Fix: Mark your IEP dates, or talk with an advisor 2–3...
“Snowbird Medicare: A Two-State Plan That Actually Works”
Snowbird Medicare: A Two-State Plan That Actually Works If you split the year between two homes, you already know about duplicate utility bills and the art of packing one jacket that somehow works in two climates. But there’s one thing snowbirds often overlook: how to...
Regular Review
Your life will change. And your plan must change with it. At our regular plan reviews we check for progress, realign to new information, and address any information that is out of date. Our support team is here for you to get you the answers you need when you need them. Regular plan reviews are just another part of doing it the right way.
Financial Services
Insurance Services
Educational Blogs
Medicare
TGW Wealth Management Locations
Topeka, Kansas
1315 SW Arrowhead Road
Topeka, KS 66604
Office: 785-213-0740
thad@tgwwealthmanagement.com
Manhattan, Kansas
210 Southwind Rd, Suite 2A
Manhattan, KS 66502
Office: 785-213-0740
thad@tgwwealthmanagement.com
Salina, Kansas
204 S. Santa Fe Ave, Ste #3
Salina, KS 67401
Office: 785-213-0740
thad@tgwwealthmanagement.com